Lump-sum investing has historically beaten dollar cost averaging in roughly two out of every three ten-year periods, according to research from Vanguard and Northwestern Mutual. But here is the twist: most people never invest a lump sum at all. They invest whatever hits their paycheck whenever it hits, and that is exactly where dollar cost averaging turns from a consolation prize into your single best money move.
If you have ever refreshed a stock ticker, watched the market dip, and frozen instead of buying, you already know the real enemy is not bad math. It is bad timing driven by emotion. Dollar cost averaging (DCA) fixes that by taking the guessing out of the equation completely, and it works whether you are investing $50 a month or $5,000.
What Dollar Cost Averaging Actually Is
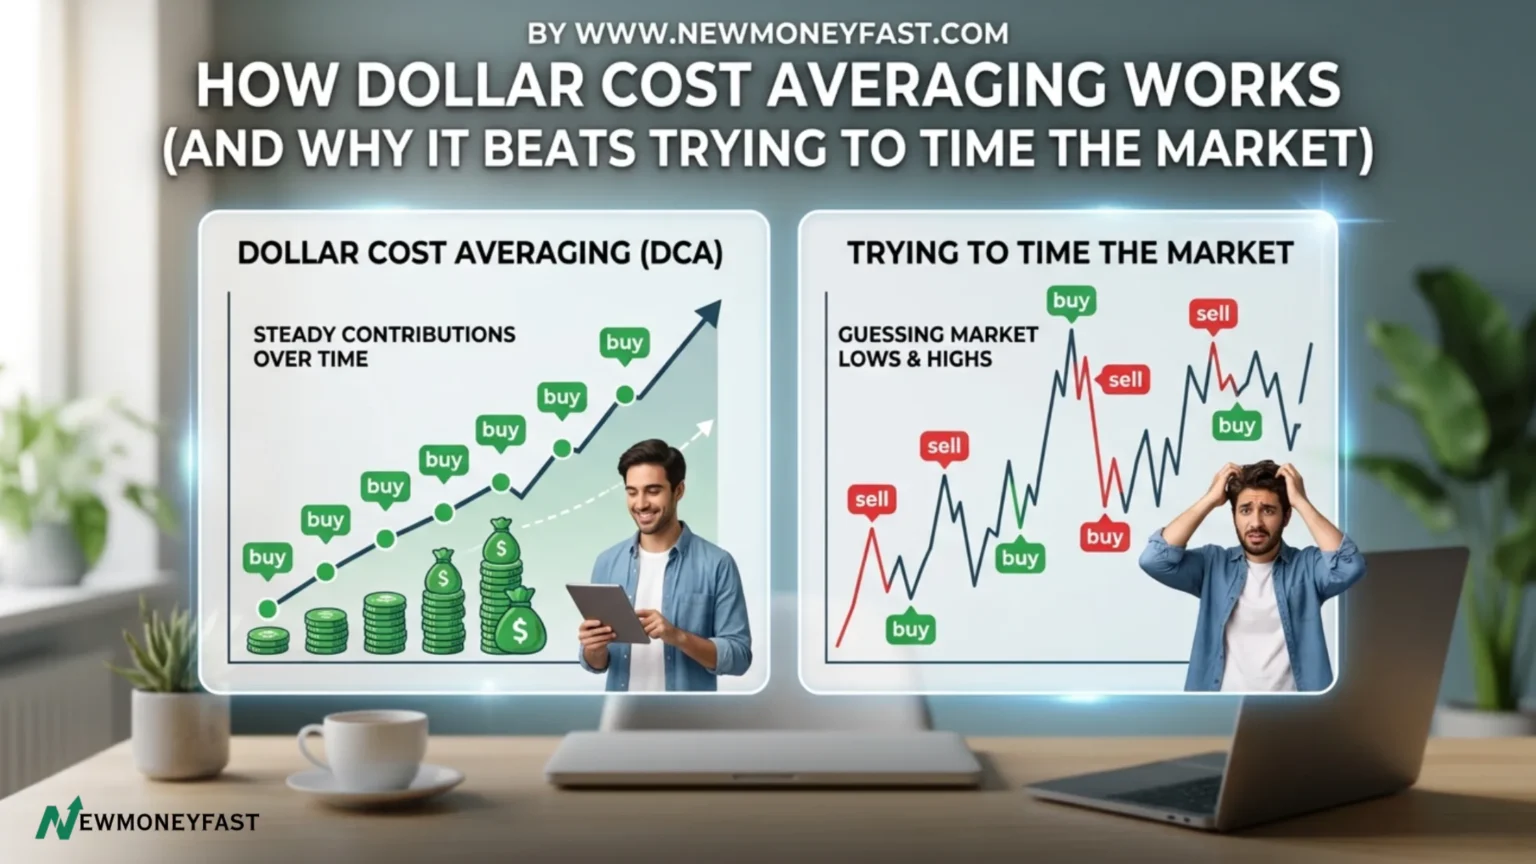
Dollar cost averaging means investing a fixed dollar amount on a set schedule, no matter what the market is doing that day. Instead of trying to buy low and sell high, you buy on autopilot every week, every two weeks, or every month. When prices are down, your fixed dollar amount buys more shares. When prices are up, it buys fewer. Over time, this smooths out your average cost per share and removes the pressure of picking the perfect entry point.
This is not a theory. It is already how most Americans invest without realizing it. Every time money leaves your paycheck for a 401(k), you are dollar cost averaging. The strategy just works even better when you extend it deliberately to a Roth IRA or taxable brokerage account.
Why It Beats Trying to Time the Market
Morningstar research shows the average equity fund investor underperforms the funds they are invested in by roughly 1.7 percentage points a year, largely because of poorly timed entries and exits. Translation: trying to outsmart the market usually costs you money instead of making you money.
A Morgan Stanley analysis of more than a thousand overlapping seven-year periods found that immediate lump-sum investing outperformed a 12-month phase-in by about 0.42 percent per year on average. That edge exists because markets trend upward more often than they fall. But that same research is a study in investor behavior, not investor comfort. Behavioral finance studies show losses feel roughly twice as painful as equivalent gains feel good, which is exactly why so many people cannot stomach investing everything at once and then freeze instead of investing anything.
Dollar cost averaging trades a small amount of theoretical return for a plan you will actually stick with. A mediocre plan you follow every single month beats a perfect plan you abandon the first time the market drops ten percent.
How to Set Up Dollar Cost Averaging This Week
1. Pick Your Account
Start with whichever account matches your goal. A Roth IRA is ideal for long-term, tax-free growth. A taxable brokerage account works for money you might need before retirement age. Either way, the mechanics of DCA are identical.
2. Automate the Contribution
Set up a recurring transfer from your checking account the day after payday, then set up a recurring buy into a low-cost index fund or ETF. Fidelity currently stands out as one of the only major brokerages that lets you schedule automatic recurring purchases directly into individual stocks and ETFs, not just mutual funds. Schwab and Vanguard offer strong automatic investing for mutual funds and robo-portfolios as well.
3. Set It and Forget It
Pick an amount you will not miss, even $50 a month, and let it run untouched for at least 12 months before you evaluate anything. The entire point of DCA is removing your own decision-making from the equation once the plan is live.
DCA vs. Lump Sum: Side by Side
| Factor | Dollar Cost Averaging | Lump Sum |
|---|---|---|
| Historical average return | Slightly lower | Higher about 2 out of 3 times |
| Emotional difficulty | Low, fully automated | High, requires investing all at once |
| Best for | Paychecks, new investors, ongoing income | Windfalls, bonuses, inheritances |
| Volatility exposure | Smoothed out over time | Full exposure immediately |
| Setup effort | 15 minutes, then automatic | One transaction, done |
| QUICK WINS SUMMARYWhat you gain: A repeatable investing system that removes emotion and guessworkTime investment: About 15 minutes to set up, then fully automaticDifficulty level: Beginner-friendlyBest for: New investors, anyone paid on a regular schedule, and people who freeze up trying to time the market |
| THE 90-DAY AUTOPILOT CHALLENGESet up one recurring automatic investment this week, no matter how small.Let it run untouched for three full paychecks.At day 90, check your account and see exactly how many shares you accumulated without lifting a finger after setup.Which amount will you start with? Reply and tell us your number. |
Visual Content Suggestions for Design Team
- Line chart comparing DCA versus lump-sum growth of $10,000 over a volatile 12-month window
- Step-by-step screenshot walkthrough of setting up a recurring investment in a brokerage app
- 90-Day Autopilot Challenge tracker graphic readers can fill in each payday
- Side-by-side comparison graphic of the DCA vs. lump sum table above, styled in brand colors
Frequently Asked Questions
Is dollar cost averaging actually a legitimate strategy?
Yes. It is used inside every workplace 401(k) in the country and is backed by decades of Vanguard, Morgan Stanley, and academic research. It is not a shortcut or a trick, it is a disciplined default.
How much money do I need to start?
Most major brokerages allow fractional shares, so you can start with as little as $1. Many new investors begin with $50 to $100 a month and increase the amount as income grows.
Will I make less money with DCA than investing a lump sum?
On average, slightly, if you already have a large sum sitting in cash. Research shows lump sum wins about two-thirds of the time. But DCA usually wins in practice because it is the strategy people actually stick with when money arrives gradually.
Which brokerage is best for setting up automatic investing?
Fidelity currently leads for recurring buys into individual stocks and ETFs. Schwab and Vanguard are strong choices if you prefer mutual funds or a robo-advisor style approach.
How long before I see real results?
Most investors will not notice a meaningful account balance for 6 to 12 months. The real payoff of DCA shows up over years, as consistent contributions compound alongside market growth.
Start Your Autopilot Investing Plan Today
You do not need a windfall to start building wealth. You need a system that runs whether you are paying attention or not. Set up your first recurring investment this week and join thousands of New Money Fast readers who are letting consistency do the heavy lifting.
Compare top brokerages for automatic investing: See our full brokerage comparison guide
Keep Reading on New Money Fast
- Robinhood vs. M1 Finance vs. Public: Best Commission-Free Brokerage for Beginners
- What Is a Roth IRA and Why Every 20-Something Needs One
- Acorns vs. Stash vs. Betterment: Which Micro-Investing App Grows Your Money Faster
Sources
Investing.com: US Dollar-Cost Averaging Vs. Lumpsum Investing
Northwestern Mutual: Dollar-Cost Averaging vs. Lump-Sum Investing
Morgan Stanley: Dollar-Cost Averaging vs Lump Sum Investing
Masterworks Academy: Dollar-Cost Averaging vs. Lump-Sum Investing
Thrivent: Pros & Cons of Dollar-Cost Averaging vs. Lump-Sum Investing
Mustachian Post: Dollar Cost Averaging vs Lump Sum
Clockwise Capital: Lump Sum vs. Dollar-Cost Averaging, What the Research Says
Elevation Financial: Dollar Cost Averaging vs. Lump Sum Investing
The College Investor: Best Automatic Investment Apps Of 2026