The best no-medical-exam life insurance companies in 2026 are Ladder and Ethos for fast online coverage up to $3 million, Banner Life and Pacific Life for big policies at low rates, and Mutual of Omaha for applicants over 50. Most healthy adults under 60 can get approved in minutes to a few weeks with no needles.
| Key Takeaways: Ladder, Ethos, and Pacific Life offer up to $3 million in coverage with no medical exam.Haven Life is no longer accepting new applications, per Haven Life’s site. Existing policies are unchanged.Mutual of Omaha ranked No. 1 in J.D. Power’s 2025 U.S. Individual Life Insurance Study with 707 points out of 1,000.No exam does not mean no checks: insurers still review prescription history, driving records, and health questions, per Policygenius. |
Why does no-exam life insurance matter right now?
Skipping the exam removes the biggest excuse to put off coverage, and the market just shifted: Haven Life stopped taking applications, and Bestow sold its insurer to Sammons Financial Group in 2024, which renamed it Lantern Insurance Company. If you shopped either brand before, compare again.
What are the 3 types of no-exam life insurance?
- Accelerated underwriting: Uses data instead of an exam for healthy applicants. Up to $3 million in term coverage, sometimes in as little as 24 hours.
- Simplified issue: A short health questionnaire. Typically up to $100,000, approved in a few days to two weeks.
- Guaranteed issue: No health questions at all. Usually up to $25,000 and the most expensive per dollar of coverage.
Coverage limits and timelines from Policygenius, updated Oct. 15, 2026.
The 8 Best No Medical Exam Life Insurance Companies
1. Ladder: Best for Flexible Coverage You Can Shrink Later
How it works: Ladder sells term life online with a few health questions and no medical exam for policies up to $3 million. Its standout feature is “laddering,” which lets you lower your coverage as your mortgage or kids’ needs shrink, cutting your premium.
Real example: Policies are issued by Amica Life, Fidelity Security Life, or S.USA Life, depending on your state, per Ladder. Terms cover the 10 to 30 years your family depends on you most. Cancel within 30 days for a full refund.
Price snapshot: Some prices start at $5 a month for a 20-year-old rated Preferred Plus buying $100,000 for 10 years (rate valid as of Apr. 7, 2026, per Ladder). Your price depends on age, health, and coverage.
Pros and cons: High no-exam limit and the ability to cut coverage without reapplying. Ladder is an agency, so the issuing carrier varies by state.
Best for: Parents and homeowners whose coverage needs will drop over time.
| Action stepQuote your target coverage, then half that amount, to see what laddering could save later. |
2. Ethos: Best for Fast Approval and Older Applicants
How it works: Ethos is a licensed agency that sells policies from several insurers through one short online application. U.S. citizens and permanent residents aged 20 to 85 can apply, and term life is available through age 69. Coverage runs up to $3 million with terms from 10 to 40 years.
Real example: Ethos says customers can be approved in as little as 10 minutes, and 700,000 families had activated a policy as of August 2026, per Ethos. Its carrier partners include Banner Life and Protective Life (both A+ from AM Best) plus TruStage and Ameritas (both A).
Price snapshot: Plans start from $30 a month, per Ethos. Ethos does not publish the age or coverage behind that figure.
Pros and cons: The widest age range on this list and same-day coverage. Not available in New York.
Best for: Applicants in their 50s to 80s and anyone who wants coverage this week.
| Action stepFinish the Ethos application in one sitting, then compare the offer with two other quotes. |
3. Banner Life (Legal & General America): Best for Low Rates on Long Terms
How it works: Banner Life, part of Legal & General America, offers no-exam term coverage to healthy applicants aged 20 to 60. It is known for long terms, up to 40 years, and competitive pricing.
Real example: Policygenius rates the Banner Life family 4.9 out of 5 and names it the cheapest no-exam option, with no-exam coverage up to $2 million. Approval can take up to 3 weeks.
Coverage snapshot: Up to $2 million with no exam and terms up to 40 years.
Pros and cons: Strong price and a rare 40-year term. Less competitive for older applicants, and slower than app-first brands.
Best for: Healthy adults in their 20s to 40s who want a long term at a low price.
| Action stepAsk for a 30-year and a 40-year quote side by side. The longer term often costs less than you expect. |
4. Pacific Life: Best for High Coverage Into Your 60s
How it works: Pacific Life offers no-exam term life for people aged 18 to 70 with coverage up to $3 million, per Policygenius. Older applicants may need an attending physician statement, a summary of records from their doctor.
Real example: Policygenius rates Pacific Life 4.8 out of 5 and names it the best no-exam term life insurer. It holds an A+ (Superior) rating from AM Best. Approval can take up to 4 weeks, and its term product is not offered in New York.
Coverage snapshot: Up to $3 million with no exam, even past 60.
Pros and cons: Top-tier financial strength and high limits for older buyers. Slower approval than app-first options.
Best for: Higher earners in their 50s and 60s replacing income or covering an estate.
| Action stepIf you are over 60, request your medical records in advance to speed up the physician statement. |
5. Protective: Best for No-Exam Permanent Coverage
How it works: Protective offers terms up to 40 years plus a rare no-exam guaranteed universal life policy. Guaranteed universal life (GUL) is permanent coverage with a fixed premium and little cash value, so it costs far less than whole life.
Real example: Per Policygenius, Protective’s no-exam GUL goes up to $1 million for ages 18 to 45 and up to $500,000 for ages 46 to 60. It holds an A+ from AM Best and a 4.8 Policygenius score. Its no-exam options are limited and not available in New York.
Coverage snapshot: Up to $1 million in lifelong, no-exam coverage.
Pros and cons: Permanent coverage without an exam is hard to find. Fewer no-exam choices than term-focused brands.
Best for: Buyers who want lifelong coverage for final expenses or a dependent with special needs.
| Action stepCompare a Protective GUL quote against a 30-year term plus investing the difference before you decide. |
6. Transamerica: Best for Young Adults Starting Out
How it works: Transamerica offers no-exam policies for adults as young as 18, with no-exam coverage up to $2 million, per Policygenius. Buying young locks in a low rate for decades.
Real example: Transamerica earns an A from AM Best and a 4.6 Policygenius score. Approval can take up to 4 weeks, and its term product is not available in New York.
Coverage snapshot: Up to $2 million with no exam from age 18.
Pros and cons: High limits for very young buyers. Slower than app-based companies and agent-driven.
Best for: New grads, newlyweds, and first-time parents.
| Action stepIf you are under 30, price a 30-year term now. Policygenius estimates premiums rise about 8% to 10% for each year you wait. |
7. Mutual of Omaha: Best for Customer Satisfaction and Applicants Over 50
How it works: Mutual of Omaha offers no-exam term life and small whole life policies built for older buyers. Its final expense whole life covers ages 45 to 85, with up to $50,000 in coverage. Simplified-issue term is available into your 70s.
Real example: Mutual of Omaha ranked No. 1 among 23 carriers in J.D. Power’s 2025 study with 707 points, against an industry average of 650. Per Policygenius, its no-exam term reaches $250,000 for ages 51 to 60 and $150,000 for ages 61 to 75, with approval in up to 2 weeks. It holds an A+ from AM Best.
Coverage snapshot: Up to $250,000 in no-exam term for ages 51 to 60.
Pros and cons: Best-in-class service and options into your 80s. Policygenius notes prices run higher than average.
Best for: Adults over 50 covering final expenses, a mortgage balance, or a spouse.
| Action stepAsk for both a term and a final expense quote, then pick the smallest policy that covers your real costs. |
8. TruStage: Best for A-Rated Coverage Through a Simple Online Process
How it works: TruStage, the brand of CMFG Life Insurance Company, issues term and whole life policies, including through the Ethos platform. That pairs a fast online application with a well-rated carrier.
Real example: Per Ethos’ carrier page, TruStage holds an A (Excellent) from AM Best as of December 2025, an A+ from S&P (September 2025), and an A2 from Moody’s (January 2026).
Ratings snapshot: A-rated across all three major agencies. Coverage and pricing depend on your application.
Pros and cons: Strong ratings and a simple process. Fewer published details on maximum no-exam limits.
Best for: Buyers who want small term or whole life coverage from a highly rated carrier.
| Action stepWhen you get an Ethos quote, check which carrier is issuing it. If it is TruStage, compare its term and whole life prices. |
Which no-exam life insurer is best for you?
| Company | Max no-exam coverage | Ages | AM Best | Approval time | Best for |
|---|---|---|---|---|---|
| Ladder | $3 million | Not published | Varies by issuer | Minutes to apply | Coverage you can shrink |
| Ethos | $3 million | 20 to 85 (term to 69) | A to A+ (by carrier) | As little as 10 minutes | Speed and older applicants |
| Banner Life | $2 million | 20 to 60 | A+ | Up to 3 weeks | Low rates, 40-year terms |
| Pacific Life | $3 million | 18 to 70 | A+ | Up to 4 weeks | High coverage in your 60s |
| Protective | $1 million (GUL) | 18 to 60 | A+ | Varies | No-exam permanent coverage |
| Transamerica | $2 million | 18 and up | A | Up to 4 weeks | Young adults |
| Mutual of Omaha | $250,000 term (ages 51 to 60) | Into the 80s | A+ | Up to 2 weeks | Service and over-50 buyers |
| TruStage | Depends on application | Depends on product | A | Depends on channel | A-rated small policies |
Sources: Policygenius (Oct. 15, 2026), Ladder, Ethos, and Ethos carrier ratings. Policygenius lists Banner Life at A, while Ethos lists A+. Published starting prices: Ladder from $5 a month and Ethos from $30 a month. Your quote varies by state, age, health, tobacco use, and coverage amount.
Does no-exam life insurance cost more?
Sometimes. Policygenius notes you may pay more than with a fully underwritten policy, mainly with simplified and guaranteed issue, where the insurer knows less about you. Smokers can pay about double. This won’t work if you have a serious health condition and want a large policy. In that case, a traditional exam may get you a better price.
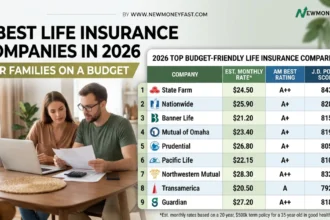
Customer satisfaction tip: J.D. Power’s 2025 study of 5,065 customers found people who bought directly from a carrier scored 696, which was 57 points higher than those who bought through an agent, per InsuranceNewsNet. State Farm (697) and Nationwide (695) placed second and third.
| Level Up: Your No-Exam Coverage PlanBeginner: Multiply your income by 10 to get a starting coverage number, then get one online quote.Pro: Collect 3 quotes from different carriers at the same coverage and term.Expert: Ladder two policies (say, a 30-year and a 15-year) so coverage drops as your mortgage does. |
| The 15-Minute ChallengeSet a 15-minute timer this week and get your first no-exam quote.Tag a friend who keeps putting off life insurance. Which company are you quoting first? Tell us in the comments. |
| Quick Wins Box Potential savings: Lock in today’s age-based rate. Each year you wait means a higher starting priceTime investment: 10 to 30 minutes per applicationDifficulty: EasyBest for: Healthy adults under 60 who want coverage in days, not months |
FAQ: No Medical Exam Life Insurance
What is the best no medical exam life insurance company?
The best company depends on your age and needs. Ladder and Ethos lead for fast online coverage up to $3 million, Banner Life for low rates on long terms, and Mutual of Omaha for applicants over 50 and top customer satisfaction.
How much life insurance can I get without a medical exam?
Healthy applicants can get up to $3 million without an exam from Ladder, Ethos, and Pacific Life. Simplified-issue policies typically top out around $100,000, and guaranteed issue around $25,000.
Is no-exam life insurance more expensive?
No-exam life insurance can cost more than a fully underwritten policy, mostly for simplified and guaranteed issue coverage, where the insurer has less health data. Healthy applicants should compare a no-exam quote against an exam-based quote before buying.
Do no-exam life insurance companies check medical records?
Yes. Most no-exam insurers check prescription history, driving records, and your answers to health questions, and older applicants may need a doctor’s statement. Answer every question honestly, because misstatements can put a claim at risk.
Is Haven Life still selling policies in 2026?
No. Haven Life says it is no longer accepting new applications, and existing policies issued by MassMutual or C.M. Life are unchanged. New shoppers should compare alternatives such as Ladder, Ethos, or Banner Life.
| Get Covered Without the NeedlesCompare no medical exam life insurance quotes from top-rated carriers in about 10 minutes, and lock in your rate before your next birthday.[AFFILIATE LINK: Compare No-Exam Life Insurance Quotes] | [AFFILIATE LINK: Get a Ladder Quote] | [AFFILIATE LINK: Get an Ethos Quote] |
Sources
- Policygenius: Best no medical exam life insurance (updated Oct. 15, 2026)
- Ladder: Term life insurance home page (rate valid Apr. 7, 2026)
- Ladder: Term life insurance details and issuing carriers
- Ethos: Life insurance home page (2026)
- Ethos: Our life insurance carriers and ratings
- Haven Life: Notice on new applications (2026)
- Bestow: Company FAQ on the sale of Bestow Life Insurance Company
- InsuranceNewsNet: J.D. Power 2025 U.S. Individual Life Insurance Study (Oct. 9, 2025)
- Business Wire: J.D. Power 2025 life insurance study release (Oct. 9, 2025)
- Mutual of Omaha: Ranked No. 1 in J.D. Power 2025 study
- J.D. Power: U.S. Individual Life Insurance Study
- Policygenius: Life insurance rates by age