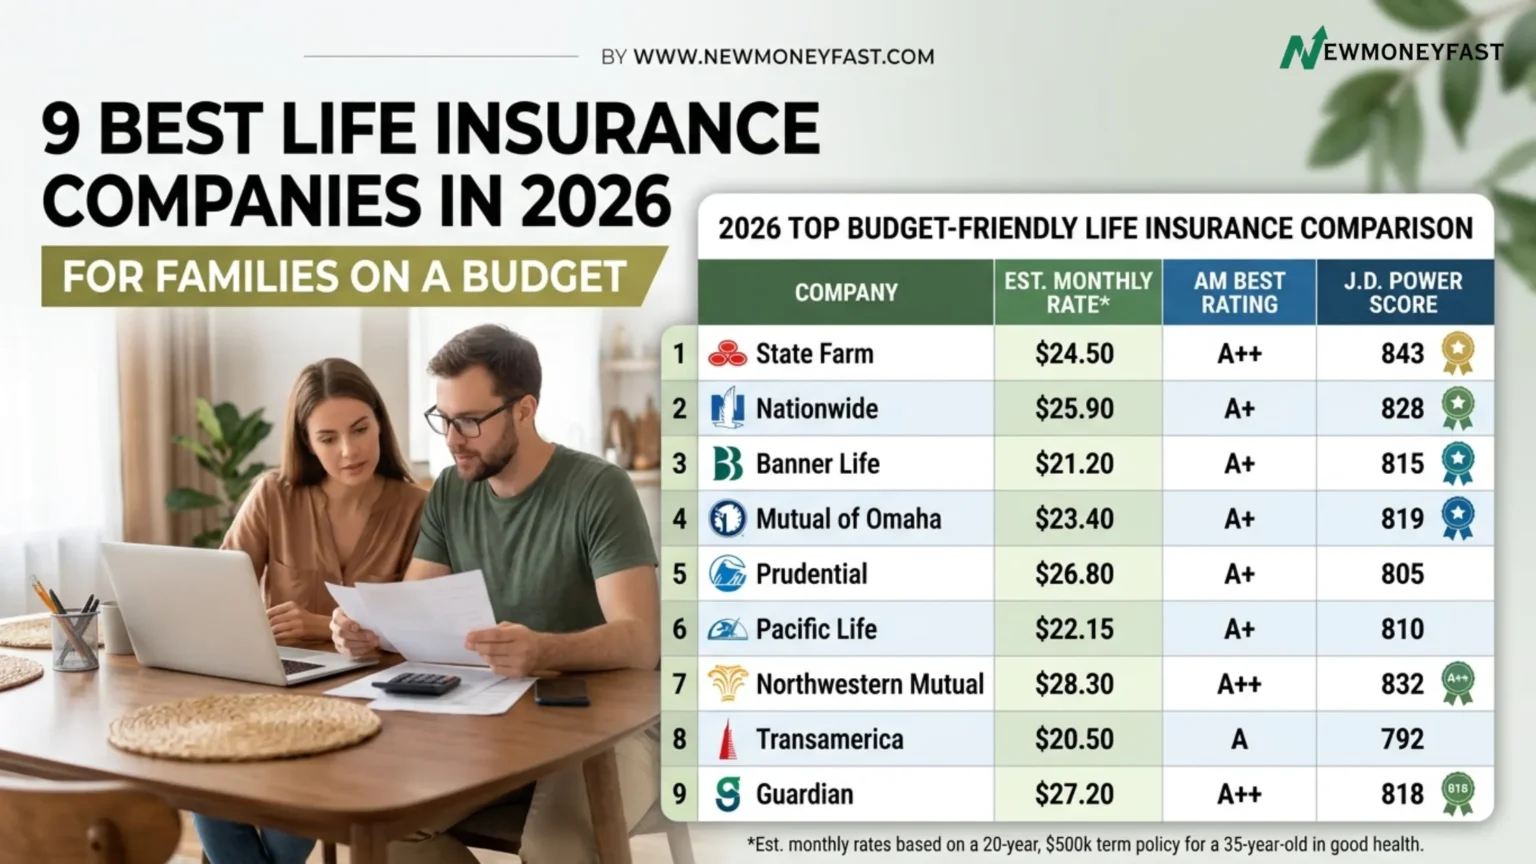
The best life insurance companies in 2026 for families on a budget are Banner Life, Transamerica, Pacific Life, and Guardian for price, plus Nationwide, State Farm, and Mutual of Omaha for service. A healthy 40-year-old typically pays roughly $26 to $59 a month for $500,000 of 20-year term coverage, depending on health class and source.
| KEY TAKEAWAYS: Banner Life and Transamerica average $37 a month for a 40-year-old woman and $46 for a man on a 20-year, $500,000 policy, about $120 to $156 a year below the market average.Nationwide ranks first in the J.D. Power 2026 life insurance study at 701, ahead of State Farm (692) and Mutual of Omaha (680). The industry average is 649.Waiting from age 30 to 40 raises the price of the same policy by roughly 52% for women and 55% for men.Cheapest is not always best: Transamerica’s complaint index is 3.86, versus 0.05 at Pacific Life.Skip Haven Life. It stopped accepting applications in January 2024. |
Why does life insurance matter for budget families right now?
Term life insurance is coverage for a fixed period, usually 10 to 30 years, that pays your family a tax-free benefit if you die during the term. It is the budget-friendly choice for most parents because it costs a fraction of permanent coverage.
J.D. Power’s October 2026 study found overall satisfaction at 649 out of 1,000 and trust down 9 points year over year, so a clean service record matters as much as price. We compared nine major US insurers on cost, financial strength, service, and fit. Your own quote will differ by state, age, and health.
Which life insurance companies have the lowest rates for families?
1. Banner Life: Lowest Rates With a Clean Complaint Record
How It Works: Banner Life sells term policies in seven lengths from 10 to 40 years, with up to $10 million of coverage. MoneyGeek’s September 2026 analysis names it the best overall term company, pairing the lowest average rates with an NAIC complaint index of 0.16 (1.00 is the expected level, so lower is better). No-exam coverage goes up to $4 million. It is not sold in New York and accepts ages 20 to 75.
Real Example: A 40-year-old woman pays an average of $37 a month ($444 a year) and a man pays $46 ($552) for a 20-year, $500,000 policy. MoneyGeek puts the market averages at $47 and $59.
Estimated Savings: $120 a year for women and $156 for men versus average, or roughly $2,400 to $3,120 over a 20-year term.
Pros and Cons: Pros: lowest average rates, low complaints, terms up to 40 years. Cons: unavailable in New York, no applicants under 20.
Best For: Healthy parents who want the lowest premium from an insurer with few complaints.
Action Step: Request a Banner Life quote, then price two competitors using identical health answers.
2. Transamerica: Low Price and a Wider Age Range
How It Works: Transamerica matches Banner Life’s average rates of $37 for women and $46 for men at age 40, accepts applicants from 18 to 80, and offers 10 to 30 year terms with up to $2 million of no-exam coverage. The tradeoff is service. MoneyGeek lists its NAIC complaint index at 3.86, far above the 1.00 expected level.
Real Example: A 40-year-old man pays about $552 a year, the same as at Banner Life. But a 78-year-old can still apply at Transamerica, while Banner Life stops at 75.
Estimated Savings: $120 to $156 a year versus the market average, matching Banner Life.
Pros and Cons: Pros: low rates, wide age range, broad health classes. Cons: high complaint index, 30-year maximum term.
Best For: Older applicants and buyers with minor health issues who are comparing several quotes.
Action Step: Look up Transamerica’s recent complaint record on the NAIC site before you apply.
3. Pacific Life: Fewest Complaints and a Big No-Exam Limit
How It Works: Pacific Life offers 10 to 30 year terms for ages 18 to 80, up to $10 million of coverage, and up to $3 million with no medical exam. MoneyGeek gives it the lowest complaint index in its analysis at 0.05 and calls it the cheapest option for young adults. Policies can convert only to a universal life policy.
Real Example: A 40-year-old woman pays an average of $38 a month ($456 a year) and a man pays $54 ($648), against market averages of $47 and $59.
Estimated Savings: $108 a year for women and $60 for men versus the average.
Pros and Cons: Pros: fewest complaints, large no-exam limit, ages up to 80. Cons: men’s rates trail Banner Life by $8 a month, and conversion is limited to universal life.
Best For: Young families and anyone who values a spotless service record.
Action Step: Ask which universal life policies you could convert to before you commit.
4. Guardian: A++ Strength at a Low Sample Price
How It Works: Guardian is NerdWallet’s top pick for term and overall life insurance, with sample rates of $26 a month for women and $31 for men on $500,000 of coverage for healthy nonsmokers. It carries an A++ AM Best rating, the highest available, per Insure.com’s 2026 ranking. Sample rates assume excellent health, so expect more with average health.
Real Example: At $26 to $31 a month, $500,000 of coverage costs $312 to $372 a year.
Estimated Savings: NerdWallet’s samples run $4 to $5 a month below New York Life ($30 for women, $36 for men), or $48 to $60 a year.
Pros and Cons: Pros: A++ strength, top overall rating, low sample rates. Cons: samples are not guaranteed quotes, and you need excellent health to reach them.
Best For: Healthy buyers who want top-tier financial strength at a low price.
Action Step: Get Guardian and New York Life quotes on the same day and compare them line by line.
Which life insurers have the best customer satisfaction?
5. Nationwide: J.D. Power’s 2026 Number One
How It Works: Nationwide ranked first in the J.D. Power 2026 U.S. Individual Life Insurance Study with 701 points, up from third in 2025, and reports top marks for trust, value for price, digital channels, and problem resolution. MoneyGeek lists its term at $45 for women and $56 for men at age 40, with 10 to 30 year terms, up to $1.5 million with no exam, and ages 21 to 55.
Real Example: A 40-year-old man pays about $672 a year ($56 a month) for 20-year, $500,000 coverage and can apply for up to $1.5 million without a medical exam.
Estimated Savings: $24 a year for women and $36 for men versus the market average, plus the service level J.D. Power scored highest.
Pros and Cons: Pros: highest satisfaction score, A+ AM Best rating, low complaint index. Cons: only ages 21 to 55.
Best For: Buyers 55 and under who want smooth service and a fast online process.
Action Step: Start an online quote and compare the price to Banner Life’s $37 to $46 benchmark.
6. State Farm: Second in J.D. Power With a Local Agent
How It Works: State Farm placed second in J.D. Power’s 2026 study at 692. NerdWallet’s sample rates for top-class applicants on a 20-year, $500,000 policy (generated Feb. 18, 2026) are $27.84 a month for a 30-year-old woman and $36.09 for a 40-year-old woman. A multi-policy discount may apply with State Farm auto insurance. AM Best moved State Farm from A++ to A+ on Nov. 14, 2025, Clark.com reports, and its complaint index is 0.38.
Real Example: A 30-year-old woman in the super preferred class pays $27.84 a month, about $334 a year. A 40-year-old woman pays about $433.
Estimated Savings: Bundle discount amounts are not published, so ask your agent. Average-health buyers will pay more than these top-class samples.
Pros and Cons: Pros: second in J.D. Power, return-of-premium option, local agents. Cons: A+ rating, not sold in Massachusetts or Rhode Island, and an agent is needed to finish an application.
Best For: Current State Farm auto or home customers.
Action Step: Ask your agent to price life insurance with and without the multi-policy discount.
7. Mutual of Omaha: Top Three Again, With Coverage to Age 80
How It Works: Mutual of Omaha placed third in J.D. Power’s 2026 study at 680, after finishing first in 2025 with 707, per the company. MoneyGeek lists average rates of $49 for women and $60 for men at 40, a complaint index of 0.51, ages 18 to 80, and up to $10 million with an exam. No-exam coverage tops out at $300,000.
Real Example: A 40-year-old woman pays about $588 a year, and a man about $720.
Estimated Savings: None on price. Expect to pay about $24 a year more for women and $12 more for men than the market average, in exchange for service.
Pros and Cons: Pros: top-three satisfaction two years running, ages up to 80, large exam-based limits. Cons: pricier than Banner Life, low no-exam cap.
Best For: Buyers in their 60s and 70s, and anyone who ranks service over price.
Action Step: Compare it with Banner Life and decide whether a $12 to $14 monthly gap is worth the service.
Which life insurers fit special situations?
8. MassMutual: A++ Strength and a Free Policy for Low-Income Families
How It Works: MassMutual holds an A++ AM Best rating and a 0.08 complaint index, Clark.com reports. Its direct online term runs 10 to 30 years with $100,000 to $3 million of coverage, an immediate decision, and 90 days to finish the medical exam with temporary coverage. Most term policies convert to permanent coverage without a second exam.
Real Example: Its LifeBridge program gives qualifying low-income families a free $50,000, 10-year term policy, with the money deposited into a trust for the children’s education.
Estimated Savings: $0 in premiums for families who qualify for LifeBridge. We found no published sample rates for paid policies, so get a quote.
Pros and Cons: Pros: A++ strength, very few complaints, conversion without a second exam. Cons: exam required, no published rate benchmark.
Best For: Low-income families and buyers who want A++ strength.
Action Step: Check LifeBridge eligibility on MassMutual’s website, then request a paid-policy quote.
9. USAA: Built for Military Families
How It Works: USAA also holds an A++ rating and a 0.12 complaint index. Level term runs 10, 15, 20, 25, or 30 years with $100,000 to $5 million of coverage, per NerdWallet. Eligibility is mostly limited to people with military ties, and members leaving the service can replace Servicemembers’ Group Life Insurance with a USAA term policy.
Real Example: An active-duty member aged 18 to 35 can add $100,000 of term coverage after marrying, buying a home, or having a baby, Clark.com notes.
Estimated Savings: USAA does not publish rates, so we have no sourced benchmark. Compare your quote with the $37 to $46 Banner Life average.
Pros and Cons: Pros: A++ strength, low complaints, life-event coverage add-ons. Cons: membership limits, and rates require a quote.
Best For: Active-duty members, veterans, and their families.
Action Step: Confirm eligibility, request a quote, and benchmark it against Banner Life.
| Also worth a quote: Northwestern Mutual (A++, complaint index 0.04, agent-only, exam usually required, dividend-paying term) and New York Life (A++, 0.29, terms up to 20 years) rarely win on price but lead on financial strength, per Clark.com.Why isn’t Haven Life on this list? It stopped accepting new applications in January 2024. NerdWallet confirms that MassMutual now services existing policies. |
How do the best life insurance companies in 2026 compare side by side?
| Company | Avg. monthly rate (20-yr, $500K) | AM Best | J.D. Power 2026 | NAIC index | Best for |
|---|---|---|---|---|---|
| Banner Life | $37 F / $46 M (age 40) | A+ | Not top 3 | 0.16 | Lowest rate with few complaints |
| Transamerica | $37 F / $46 M (age 40) | A- or higher | Not top 3 | 3.86 | Applicants up to age 80 |
| Pacific Life | $38 F / $54 M (age 40) | A+ | Not top 3 | 0.05 | Fewest complaints, big no-exam limit |
| Guardian | $26 F / $31 M (sample) | A++ | Not top 3 | Low | A++ strength at a low price |
| Nationwide | $45 F / $56 M (age 40) | A+ | 701 (1st) | Low | Top satisfaction, no-exam option |
| State Farm | $36 F / $43 M (age 40, top class) | A+ | 692 (2nd) | 0.38 | Auto and home bundlers |
| Mutual of Omaha | $49 F / $60 M (age 40) | A+ | 680 (3rd) | 0.51 | Ages 60 to 80, service first |
| MassMutual | Quote needed | A++ | Not top 3 | 0.08 | Low-income families, A++ seekers |
| USAA | Quote needed | A++ | Not top 3 | 0.12 | Military families |
| Market average | $47 F / $59 M (age 40) | n/a | 649 (industry) | 1.00 | Benchmark for comparison |
Rates: average monthly cost for a 40-year-old nonsmoker in average health from MoneyGeek (Sep. 23, 2026). State Farm: NerdWallet (Feb. 18, 2026, super preferred class). Guardian: NerdWallet sample for healthy nonsmokers. Ratings: AM Best via Clark.com (Jan. 2026) and Insure.com. J.D. Power: 2026 study (top three published). Health classes differ, so rates are not directly comparable.
Does waiting to buy life insurance cost more?
Yes. MoneyGeek shows a $500,000, 20-year policy averaging $31 for women and $38 for men at 30, then $47 and $59 at 40, then $102 and $137 at 50. Buying a decade earlier cuts the monthly bill by about a third and locks the rate for the full term.
| THE 15-MINUTE QUOTE CHALLENGELevel 1, Beginner: Get one quote from Banner Life or Transamerica.Level 2, Pro: Get three quotes using identical health answers, and check each insurer’s complaint index.Level 3, Expert: Compare conversion deadlines and riders such as waiver of premium and accelerated death benefit on your top two.Tag a friend who just had a baby or bought a house. They need this today. |
| QUICK WINSTotal potential savings: $120 to $156 a year versus the market average, or about $2,400 to $3,120 over a 20-year term.Time investment: 15 to 30 minutes to apply online. Exam-based policies take two to six weeks to underwrite.Difficulty: Easy to medium.Best for: Parents, new homeowners, and anyone with dependents who counts on their income. |
Visual suggestions
- Bar chart of average monthly rates for a 40-year-old woman and man by insurer, with the $47 and $59 market averages as reference lines.
- Scorecard graphic of the J.D. Power 2026 top three (701, 692, 680) against the 649 industry average.
- Infographic showing how the price climbs at ages 30, 40, and 50.
- Screenshot of the NAIC complaint lookup, annotated to show where to find the complaint index.
Frequently asked questions
Who has the cheapest life insurance in 2026?
Banner Life and Transamerica tie for the lowest average rates, at $37 a month for a 40-year-old woman and $46 for a man on a 20-year, $500,000 policy, per MoneyGeek. Banner Life has far fewer complaints. Your quote will vary by state, health, and tobacco use.
How much life insurance does a family need?
A common starting point is about 10 times your annual income, according to MoneyGeek. A needs-based calculation that counts your mortgage, debts, education costs, and dependents is more accurate.
Is term life insurance cheaper than whole life?
Yes, by a wide margin. A 40-year-old pays an average of $47 (women) or $59 (men) a month for $500,000 of term, while MoneyGeek puts the cheapest $500,000 whole life quote at $504 for women and $521 for men.
Does smoking change life insurance rates?
Yes, it more than triples them. At age 40, women pay $148 a month as smokers versus $47 as nonsmokers, and men pay $194 versus $59, per MoneyGeek. Many insurers reconsider nonsmoker rates after 12 months nicotine-free.
Can I still buy Haven Life?
No. Haven Life stopped accepting applications in January 2024, per Policygenius. MassMutual services existing policies and sells term life directly online.
| READY TO LOCK IN A LOWER RATE?Compare quotes from several of the best life insurance companies for your family in about 15 to 30 minutes, using the same health answers each time. Locking in a rate today beats paying more next year.[AFFILIATE LINK PLACEHOLDER: licensed life insurance quote tool]Quote tools are not insurers and are not ranked in this article. |
Sources
- J.D. Power, 2026 U.S. Individual Life Insurance Study (Oct. 8, 2026)
- MoneyGeek, 7 Best Term Life Insurance Companies (updated Sep. 23, 2026)
- MoneyGeek, Cheapest Life Insurance Companies (2026)
- Clark.com, Best Term Life Insurance Companies (AM Best and NAIC data, Jan. 2026)
- NerdWallet, State Farm Life Insurance Review (Feb. 24, 2026)
- NerdWallet, Compare Life Insurance Quotes (2026)
- NerdWallet, USAA Life Insurance Review (2026)
- NerdWallet, Haven Life Insurance Review (2026)
- Policygenius, Haven Life Review
- Coverager, Haven Life No Longer Accepting Applications
- Nationwide, Nationwide Tops J.D. Power 2026 Customer Satisfaction Study
- Mutual of Omaha, Ranked No. 1 in J.D. Power 2025 Life Insurance Study
- Insure.com via Stacker, Best Life Insurance Companies of 2026
- NAIC, Consumer Information Source (complaint index lookup)
- AM Best, financial strength ratings